Job cost tracking records labour, materials, subcontractor spend and expenses against each individual job so you can calculate its real margin, not a guess based on the quote you sent. Get the inputs right and you can spot a job haemorrhaging money before it finishes, not three weeks after you've invoiced it.
The immediate action is simple: start assigning labour hours and direct costs to jobs today, even before you've built a perfect system. A rough job costing habit beats a flawless one you never start.
This article covers:
- What to record against every job, and how to structure it
- How to allocate overhead so margins reflect reality, not fantasy
- The reporting cadence and KPIs that catch overruns early
- What software should actually do for you, and how Curcle fits
Key Takeaways
Reliable job cost tracking depends on recording labour, materials and overhead consistently, then reviewing margin data often enough to correct course mid-job.
| Point | Details |
|---|---|
| Record six cost categories | Track labour, labour burden, materials, subcontractor costs, travel and committed costs against every job. |
| Allocate overhead deliberately | Apply a predetermined overhead rate (overhead ÷ labour base) so margins reflect real business costs. |
| Match reporting cadence to job length | Run weekly reports on short jobs and monthly reports on standard projects, per RICS practice standards. |
| Watch four core reports | Estimate vs actual, job profitability by phase, labour productivity and cost-to-complete catch overruns early. |
| Choose software that reduces field friction | Curcle connects jobs, timesheets, stock and invoicing so costs post to the right job automatically. |
Table of Contents
- What costs do you need to record for job cost tracking?
- How do you allocate overhead so job margins tell the truth?
- Setting up cost codes and timesheet rules that actually work
- What reports and KPIs catch overruns before they cost you?
- What should job costing software actually do for you?
- Practitioner perspective: the failures we've seen and fixed
- Where the industry gets job cost tracking advice wrong
- How Curcle supports job cost tracking day to day
- Sources
What costs do you need to record for job cost tracking?
Every job needs six categories of cost recorded against it, consistently, from day one. Miss one and your margin figure lies to you.
- Direct labour — hours worked by employees on that specific job, at their loaded hourly rate.
- Labour burden — National Insurance, pension contributions, holiday pay and benefits sitting on top of gross wages, often 20 to 30% extra that people forget to add.
- Materials and parts — anything bought or drawn from stock specifically for the job.
- Subcontractor costs — invoiced amounts from third parties working under your job number.
- Travel and expenses — mileage, parking, accommodation, anything an engineer claims back.
- Plant, hire and committed costs — equipment hire and purchase orders raised but not yet invoiced, which still eat into margin the moment they're committed.
Stock withdrawals need different treatment from direct purchases. When an engineer pulls a part from your van stock, that cost should hit the job at your standard cost price, not zero, otherwise every job using stocked parts looks artificially profitable.
Pro Tip: Build a one-page job cost sheet with columns for budgeted vs actual against each category above. If a job is over budget on labour before it's even 60% complete, that's your cue to intervene, not wait for the final invoice.
How do you allocate overhead so job margins tell the truth?
A job can show a healthy margin on paper and still leave the business worse off at year end. That gap is almost always unallocated overhead sitting on the P&L instead of being spread across the jobs that actually consumed it, as Edgestrat Finance explains in its guide to overhead allocation.
The fix is a predetermined overhead rate. Here's the method:
- Total your annual overhead: rent, insurance, admin salaries, vehicles, office costs.
- Choose an allocation base, usually total labour hours or total labour cost across the business.
- Divide overhead by the base to get a rate, for example an overhead percentage applied on top of labour cost.
- Apply that rate to every job at estimate stage, and again as actual costs are logged.
Labour tends to be the sensible allocation driver because labour activity is what usually pulls in the other overhead resources, vehicles, supervision, office support, alongside it. Beancount's job costing guide recommends setting this rate early in the year and reconciling any small variance at year end rather than chasing perfect precision on every job.
Skip this step and your estimating stays optimistic. Jobs that look profitable individually can still leave the business short.
Setting up cost codes and timesheet rules that actually work
Good job cost data depends on structure decided before you start, not fixed afterwards. RICS's New Rules of Measurement offers a useful model here: a consistent cost breakdown structure that lets you compare estimate to actual across every job and phase, rather than reinventing categories each time.
- Design a minimal cost-code list — labour, materials, subcontractor, travel, plant, overhead. Six or seven codes is usually enough; dozens of codes just creates confusion in the field.
- Set timesheet rules — who logs hours, against which job number, and by when. Same-day entry beats end-of-week guesswork every time.
- Assign ownership — one person creates jobs, engineers log time and materials, a manager reviews and approves before month-end close.
- Run a monthly reconciliation — check timesheet totals against payroll, and committed purchase orders against invoices received.
Pro Tip: Lock timesheet entry to the day it happened wherever you can. Data entered a week late is data half-remembered.
What reports and KPIs catch overruns before they cost you?
Four reports do most of the work: estimate versus actual, job profitability by phase, labour productivity, and a committed-costs or work-in-progress adjustment that captures purchase orders raised but not yet billed.
Cadence should match job length. RICS's practice standards on cost reporting note that monthly reporting is the norm in UK construction practice, but shorter jobs need weekly checks because a month is often longer than the whole job.
- Gross margin by job — the headline number, ideally including allocated overhead.
- Cost-to-complete — what's left to spend versus what's left in the budget.
- Estimate variance — where actual costs are drifting from the original quote, and by how much.
- Labour utilisation — billable hours against hours paid, a strong early signal of scheduling problems.
None of these reports matter if nobody acts on them. A job running 15% over on labour by the halfway point should trigger a resourcing conversation immediately, not a note in a spreadsheet. Use the estimate variance report to decide whether a client conversation about scope is overdue, and use cost-to-complete to decide whether to pull an engineer off a job before it erodes further.
What should job costing software actually do for you?
The processes above only stick if the software behind them removes friction rather than adding it. Look for these capabilities before anything else:
- Job budgets set at creation, so every job has a target to measure against from day one.
- Time capture tied directly to job numbers, ideally from a mobile app engineers already use.
- Expense and materials assignment that lets stock withdrawals and purchases both post to the right job.
- Subcontractor cost tracking against the same job structure as internal labour.
- An offline-capable mobile app with photo and document capture, because signal drops out on half the sites you'll ever work.
- An audit trail showing who entered what, and when.
- Integration with accounting and invoicing, so job costs don't need re-keying into a separate finance system.
The clearest adoption signal is how little effort it takes an engineer to log a cost in the field. If it takes more than a couple of taps, adoption drops and your data quality drops with it.
Practitioner perspective: the failures we've seen and fixed
Curcle grew out of a real UK service and engineering business, not a whiteboard exercise in software design. That background shapes every decision differently from a platform built purely to look good in a demo.
The recurring failures we've watched businesses hit are consistent:
- Job data scattered across spreadsheets, WhatsApp messages and paper timesheets, reconciled weeks late.
- Office teams re-keying engineer notes because field data arrives in the wrong format.
- Managers discovering a job ran over budget only when the final invoice lands.
Integrating jobs, stock and timesheets into one connected system removes most of that reconciliation effort. When a technician logs a part against a job on their phone, that cost hits the job cost sheet immediately, not after someone in the office transcribes it.
Minimise the number of taps a field engineer needs to log a job cost. Every extra step in the mobile workflow is a reason someone skips it, and skipped entries are where job costing data quietly falls apart.
— Luke Herridge
Where the industry gets job cost tracking advice wrong
Most guidance on this topic reads like a feature list: track this, report that, buy software with these modules. It rarely says what actually determines whether job costing works inside a real business, which is discipline at the point of data entry, not the sophistication of the reporting dashboard afterwards.
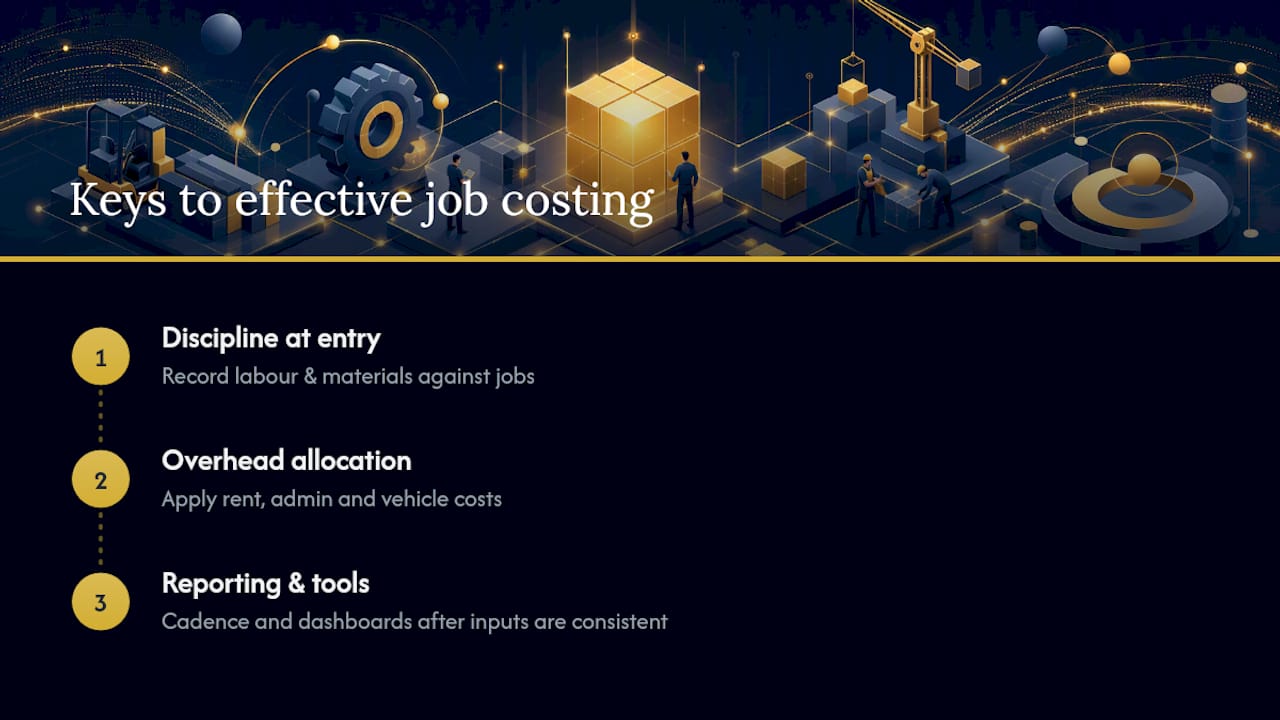
The overhead allocation step gets underrated the most. Plenty of businesses track labour and materials carefully, then skip overhead entirely because it feels like an accounting exercise rather than an operational one. It isn't. A job that looks 20% profitable without overhead applied can be break-even or worse once you spread rent, admin and vehicle costs across it properly. That's the number that should drive your next quote, not the one before overhead.
If you're starting from nothing, don't try to build the perfect cost-code structure first. Start recording labour and materials against jobs this week, however roughly. Add overhead allocation once that habit is established. Reporting cadence and software sophistication matter, but they're solving a problem you don't have yet if the basic inputs aren't landing consistently.
How Curcle supports job cost tracking day to day
Curcle brings the checklist above into one connected field service management platform rather than leaving you to stitch together spreadsheets, a timesheet app and separate accounting software.
Jobs, timesheets, stock and invoicing sit in the same system, so labour hours and materials post to the correct job automatically instead of needing manual reconciliation at month-end. The mobile app is built for field use, with minimal taps for engineers logging time or parts against a job, which is what keeps job cost data accurate in the first place. For compliance-led trades running PPM, F-Gas or LOLER work, that same job record carries certificates and asset history alongside the cost data, useful if you work in building maintenance or similar asset-heavy environments.
If you want to see whether better job-level visibility would move the needle for your business, try the savings calculator or book a walkthrough of the platform to see how job budgets, overhead application and reporting work together in practice.
Sources
- Stop Losing Profit: The Contractor’s Guide to Overhead Allocation — Edgestrat Finance
- New rules of measurement — RICS (NRM 1)
- Beancount